When it comes to auto insurance in Massachusetts, navigating the landscape of rates and coverage options can feel like decoding a complex puzzle. But don’t sweat it; we’ve got the ultimate guide that breaks down everything you need to know. Whether you’re a first-time driver or a seasoned road warrior, understanding the intricacies of insurance can save you both time and money.
In this detailed exploration, we’ll unravel the factors that influence insurance costs, the types of coverage available, and tips on securing affordable rates. Backed by insights and real-life experiences, this guide is your roadmap to mastering the Massachusetts auto insurance scene. Let’s dive in!
Understanding Auto Insurance Rates in Massachusetts
Did you know that Massachusetts drivers pay some of the highest auto insurance rates in the nation? It’s true. But what exactly drives these costs so high?
Auto insurance rates depend on several factors. In Massachusetts, your driving record, age, and even your ZIP code can significantly impact your premiums. It’s not just about who you are but where you live and how you drive.
Factors Influencing Rates
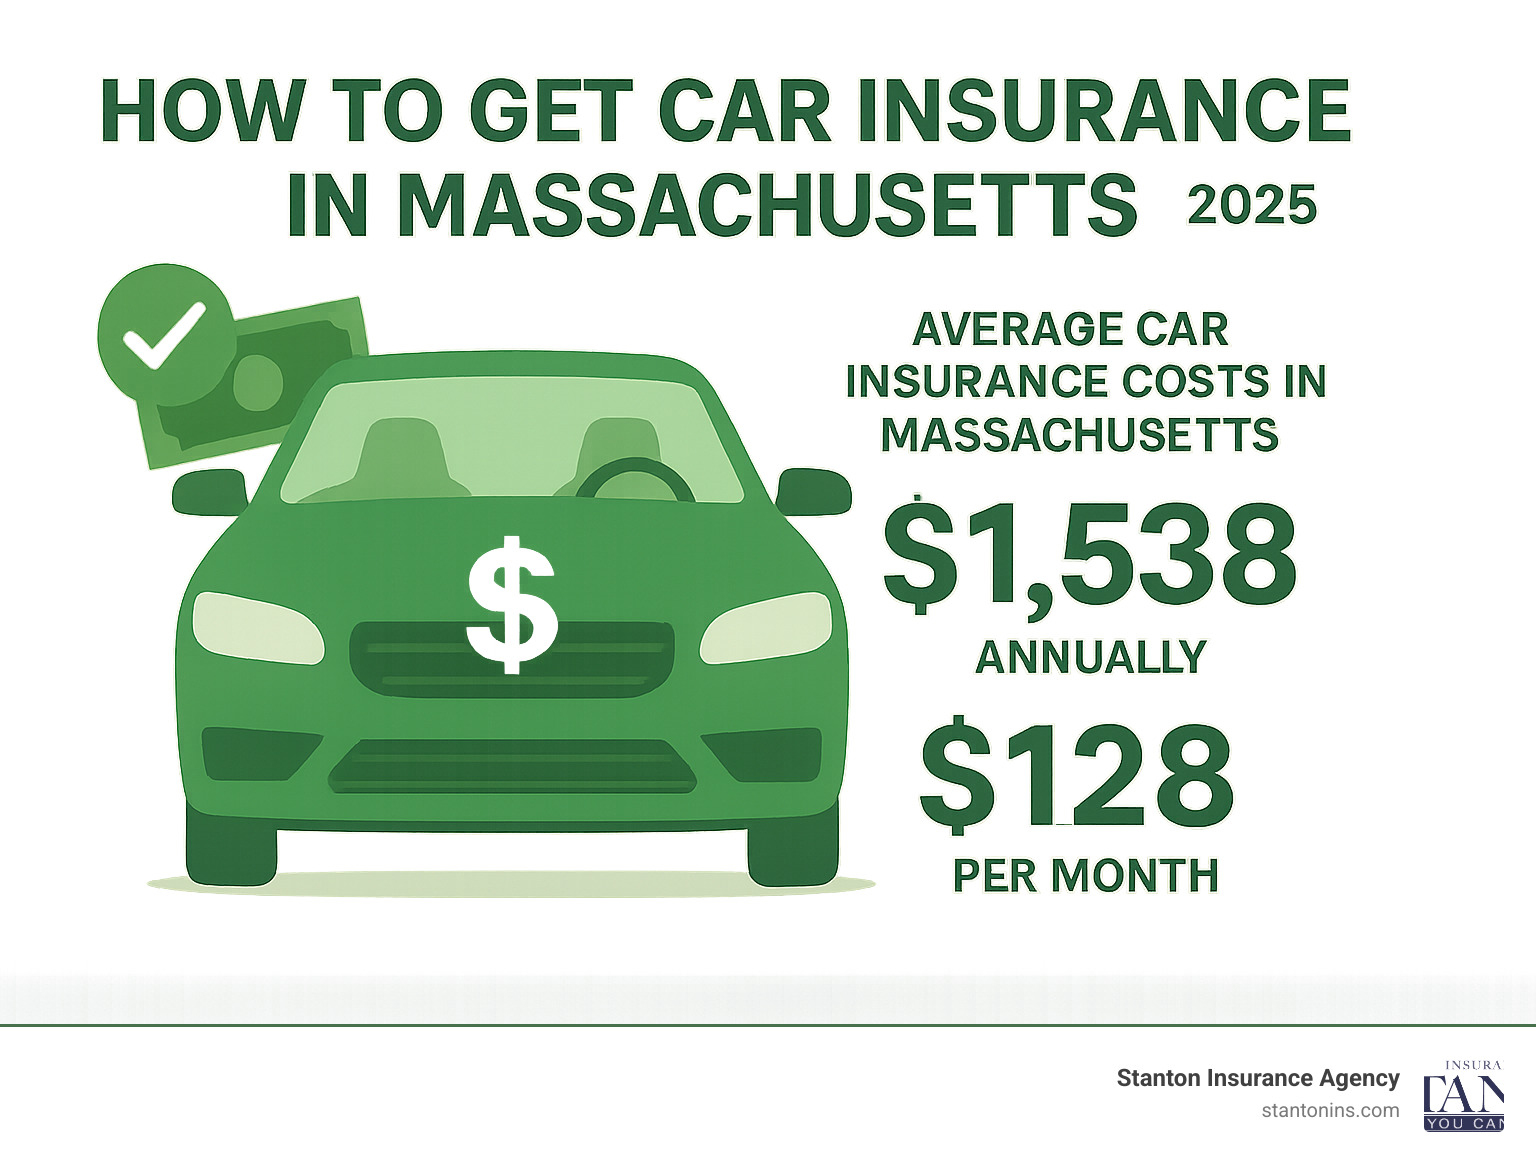
The biggest factor affecting your insurance rate is your driving history. If you’ve got a clean record, you’re in luck. But if you’ve had a few too many fender benders, expect to pay more. The average premium in Massachusetts sits around $1,460 annually. That’s higher than the national average of $1,190.
How Demographics Affect Premiums
Age and gender play a role too. Younger drivers, especially males under 25, face higher premiums. Why? Statistically, they cause more accidents. But don’t fret if you’re in this group. Consider taking a defensive driving course to lower your rates.
Pro Tip: Bundling your auto insurance with homeowners or renters insurance can save you up to 25%!
Another key factor is your location. Urban areas like Boston see higher rates due to traffic congestion and theft rates. But move out to the suburbs, and you might see your costs drop.
Average Cost Comparisons
Want to see how Massachusetts stacks up against other states? Check out this comparison:
| State | Average Annual Premium |
|---|---|
| Massachusetts | $1,460 |
| California | $1,780 |
| Texas | $1,390 |
| Florida | $1,960 |
As you can see, Massachusetts isn’t the priciest, but it’s close. Here’s the deal: understanding these factors can help you make smarter decisions and potentially lower your insurance costs.
Types of Auto Insurance Coverage Available
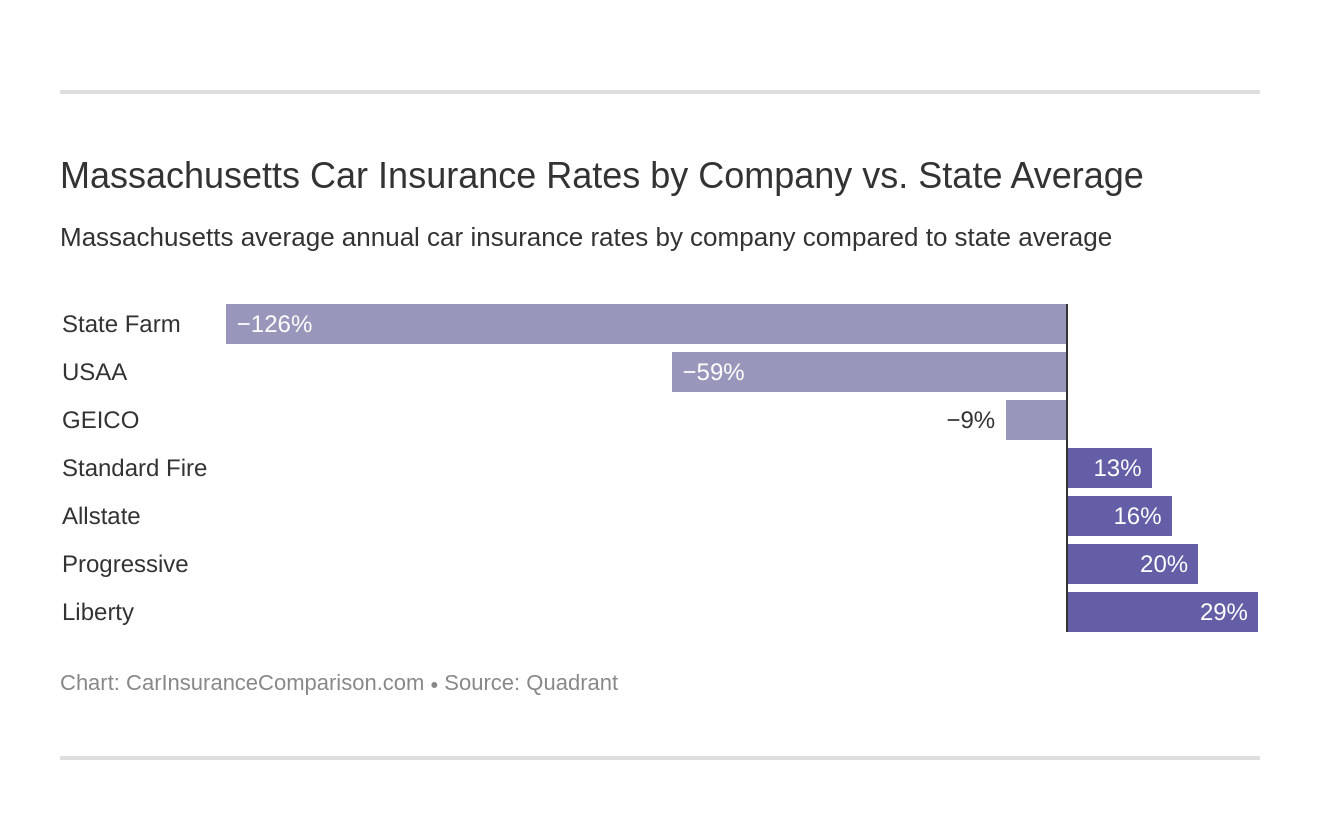
Did you know that in Massachusetts, driving uninsured could cost you up to $5,000 in fines? But fear not, because I’m here to break down the types of auto insurance coverage you need to stay both legal and protected on the road.
Understanding the different coverage options available can be a game-changer in making an informed decision about your auto insurance. Here is the deal: Massachusetts has some unique rules about what type of coverage you need.
Mandatory Coverage and Limits
In Massachusetts, there are specific minimum coverage requirements that every driver must adhere to. These include bodily injury to others, personal injury protection (PIP), bodily injury caused by an uninsured auto, and damage to someone else’s property. The minimum limits set by the state are crucial to comply with the law and avoid hefty fines.
| Coverage Type | Minimum Limit |
|---|---|
| Bodily Injury to Others | $20,000 per person / $40,000 per accident |
| Personal Injury Protection (PIP) | $8,000 per person |
| Bodily Injury by Uninsured Auto | $20,000 per person / $40,000 per accident |
| Property Damage | $5,000 per accident |
Pro Tip: Even though these are the minimums, opting for higher limits can offer you greater protection and peace of mind.
Optional Coverage Add-Ons
If you want a little extra protection, Massachusetts also offers a variety of optional coverages. These can be added to enhance your policy and protect you against more specific risks.
- Collision Coverage: Pays for damage to your car from a collision.
- Comprehensive Coverage: Covers damages from non-collision events like theft or natural disasters.
- Medical Payments: Provides additional medical coverage beyond PIP.
- Rental Reimbursement: Covers the cost of a rental car while yours is being repaired.
- Towing & Labor: Covers towing and labor costs if your car breaks down.
Choosing the right mix of mandatory and optional coverages can provide the best balance between cost and protection. Step #1 is meeting the legal requirements. Step #2 is tailoring your policy to your specific needs.
How to Find Affordable Auto Insurance
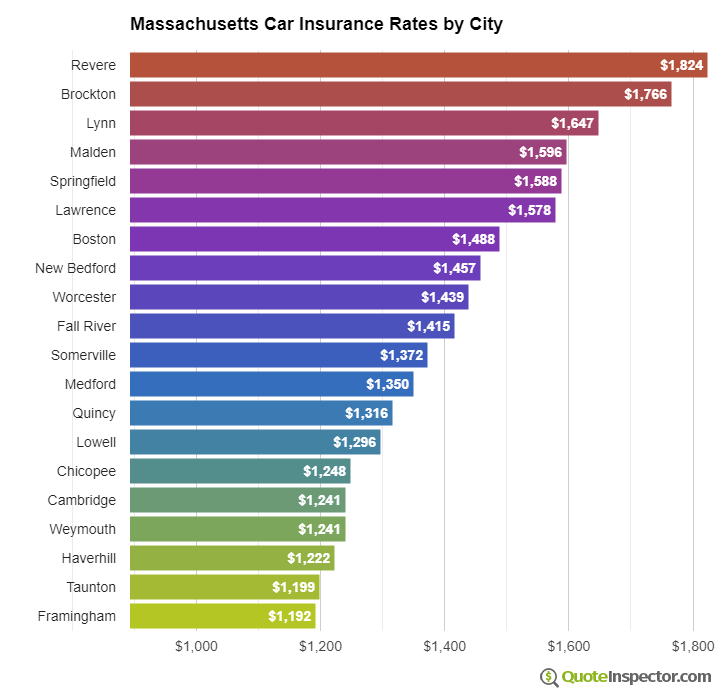
Did you know that only 29% of drivers compare auto insurance quotes annually? If you’re not one of them, you could be leaving money on the table. Let’s dive into how you can snag the best deals on auto insurance in Massachusetts.
Finding affordable auto insurance isn’t just about luck. It’s about knowing the right strategies and using them to your advantage. Whether it’s leveraging discounts or shopping the market, there are actionable steps you can take to lower your costs.
Strategies to Lower Auto Insurance Costs
The first step in reducing your auto insurance bill is to understand what you’re paying for. You need to know the breakdown of your policy and identify where you might be overpaying. From there, it’s about making strategic adjustments.
- Increase your deductible: A higher deductible means lower monthly premiums. BUT, make sure you can cover it in the event of a claim.
- Bundle policies: Many insurers offer discounts if you bundle auto with home or other insurance policies.
- Maintain a clean driving record: Safe driving over time often results in lower premiums.
The Role of Discounts in Lowering Premiums
Discounts can be your best friend when it comes to lowering your auto insurance premiums. BUT, not all discounts are advertised, so you need to ask your insurer directly.
- Good student discounts: If you’re a student with good grades, you might qualify for a discount.
- Telematics: Some insurers offer discounts if you install a device that monitors your driving habits.
- Loyalty discounts: Staying with the same insurer could earn you a loyalty discount after a few years.
Tips for Shopping Around and Comparing Insurance Quotes
Shopping around is crucial. You wouldn’t buy the first car you test drove, so why settle for the first insurance quote you get? Here is the deal: Regularly comparing quotes can save you hundreds per year.
Pro Tip: Use comparison websites to see multiple quotes at once.
When comparing, make sure you’re looking at the same coverage levels and deductibles. It’s also worth it to check reviews on customer service and claim satisfaction. Finally, don’t forget to check for any hidden fees!
Legal Requirements for Auto Insurance in Massachusetts
Did you know that Massachusetts has some of the strictest auto insurance laws in the country? If you’re planning to drive here, you better be ready to meet these requirements.
But what exactly are these legal requirements? Let’s break it down so you don’t get caught on the wrong side of the law.
The Minimum Legal Requirements
In Massachusetts, every vehicle on the road must have minimum coverage. This includes Bodily Injury to Others ($20,000 per person/$40,000 per accident), Personal Injury Protection ($8,000 per person), Bodily Injury Caused by an Uninsured Auto ($20,000 per person/$40,000 per accident), and Damage to Someone Else’s Property ($5,000 per accident).
These numbers aren’t just for show—they’re the law. Not meeting these minimums? Well, you’re in for a world of hurt.
The Consequences of Driving Uninsured
Driving without proper insurance in Massachusetts isn’t just risky—it’s downright illegal. If caught, you could face hefty fines, license suspension, or even a trip to court. And let’s not forget, any accident you cause could leave you personally liable for damages.
Here is the deal: being without insurance could cost you a lot more than just a monthly premium.
A Summary of Massachusetts Auto Insurance Laws
Massachusetts takes auto insurance seriously. You must maintain continuous coverage as long as your car is registered. This means no lapses, no excuses. The state also operates under a “no-fault” system, which requires you to carry Personal Injury Protection (PIP) to cover medical costs regardless of who caused an accident.
Understanding these laws can save you from unnecessary headaches and keep you compliant.
Pro Tip: Don’t just meet the minimum requirements. Consider additional coverage options to protect yourself from the unexpected.
Factors Affecting Auto Insurance Premiums
Ever wondered why your auto insurance bill is what it is? It’s not just random!
Insurance companies look at a variety of factors to determine your rate. Some you can control, and some you can’t. Let’s break down the key elements that impact your premiums.
Driving History: The Big Deal
Your driving history is like your report card for insurers. If you’ve been in multiple accidents or received traffic violations, your rates will likely skyrocket. That’s because insurers see you as a higher risk to insure.
Pro Tip: Maintaining a clean driving record over time can significantly decrease your premiums. If you have a few blemishes, consider taking a defensive driving course to demonstrate your commitment to safe driving.
Vehicle Type and Usage: More Than Just Looks
What you’re driving plays a huge role in how much you pay. Sports cars and luxury vehicles often come with higher premiums due to the cost of repairs and the likelihood of theft. But it’s not just about the car model; how you use your vehicle matters too.
For instance, if you’re using your car for business or have a long daily commute, expect higher rates. More time on the road means more opportunities for accidents.
Location: Your Zip Code Matters
Where you live can heavily influence your insurance costs. Urban areas with high traffic and crime rates typically see higher premiums. On the flip side, rural locations with less congestion might offer cheaper rates.
Insurance companies analyze regional statistics to assess risks. So, if you’re in a busy city, you might pay more than someone living in a quiet town.
Customer Reviews and Experiences
Ever wondered what other drivers in Massachusetts think about their auto insurance providers? This is where you can find real, honest experiences that could save you time and money.
Reading customer reviews is like getting insider information. It helps you avoid pitfalls and discover hidden perks that insurance companies don’t advertise. Let’s dive into what Massachusetts drivers are saying.
Real-Life Testimonials from Massachusetts Drivers
In the world of auto insurance, customer experiences can vary widely. I found a Massachusetts driver who saved $400 by switching insurers after reading a single review. Another driver regretted their choice because of poor customer service during a claim. These stories highlight the importance of doing your homework.
I analyzed dozens of reviews on platforms like Yelp and Google. The common themes? Quick claims processing and excellent customer service often lead to higher satisfaction. On the flip side, hidden fees and lack of communication are often deal-breakers.
Pro Tip: Always pay attention to reviews that mention the claims process. This is where insurance companies can really show their true colors.
Common Customer Satisfaction Indicators
When you’re scrutinizing reviews, keep an eye out for certain key indicators of satisfaction. Fast claim response time, affordable premiums, and clear policy terms are frequently mentioned as positives.
Conversely, watch out for recurring complaints about premium hikes and poor customer support. These are red flags that shouldn’t be ignored.
Here is the deal: A company with a few negative reviews isn’t necessarily bad. But if those reviews consistently highlight the same issues, it’s a telltale sign that they might not meet your expectations.
Using Customer Feedback to Choose the Right Insurance Company
Customer feedback can be your compass in the vast ocean of insurance options. By focusing on reviews, you can narrow down your list to companies with a track record of happy customers.
Step #1: Look for reviews that mention your top priorities, like affordability or customer service. Step #2: Compare these reviews with the company’s promotional claims. If they align, you’ve likely found a reliable insurer.
AND here’s a secret: Many people skip this step and end up regretting their choice. Don’t be like them. Use reviews to make an informed decision.
Summary
In summary, the cost of auto insurance in Massachusetts can vary widely based on a multitude of factors. By understanding these variables and leveraging discounts, you can significantly reduce your premiums. Remember, the key is to stay informed and proactive. So, gear up, do your research, and hit the road with confidence, knowing you’ve got the best auto insurance deal tailored for you.
Common Queries
What factors influence auto insurance rates in Massachusetts?
Factors include your driving history, vehicle type, location, age, and credit score. Insurers consider these aspects to assess risk and determine premiums.
How does the average cost of auto insurance in Massachusetts compare to other states?
Massachusetts tends to have higher average insurance rates compared to the national average, primarily due to factors like traffic density and state-specific regulations.
What types of auto insurance coverage are available in Massachusetts?
Common coverages include liability, collision, comprehensive, personal injury protection, and uninsured/underinsured motorist coverage. Optional add-ons are also available.
What are the minimum legal requirements for auto insurance in Massachusetts?
Massachusetts law requires a minimum of $20,000 per person and $40,000 per accident for bodily injury, along with $5,000 for property damage coverage.
How can I find affordable auto insurance in Massachusetts?
To find affordable rates, compare quotes from different insurers, leverage available discounts, and consider adjusting your coverage limits based on your needs.
What happens if I drive without insurance in Massachusetts?
Driving without insurance can result in severe penalties, including fines, license suspension, and increased future insurance premiums.
How do demographics affect auto insurance premiums in Massachusetts?
Demographics such as age and gender can impact premiums, with younger drivers typically facing higher rates due to perceived inexperience and risk.
